The $38B Visa/Mastercard Settlement: What Changes at Your Register
The headlines say Visa and Mastercard agreed to a $38 billion settlement over swipe fees. So is your processing bill about to drop? A little. Here's what the Visa Mastercard settlement actually changes at your register, what it doesn't touch, and the math on what it's really worth to a local business.
By the MTech Distributors team
You probably saw the headlines: Visa and Mastercard agreed to a $38 billion settlement with merchants over swipe fees. A lot of owners read that and figured their processing bill was about to get a lot smaller.
It's real, and it's a big deal for the industry. But for a local business, the savings are smaller than the headline. Here's what the Visa Mastercard settlement actually changes, what it doesn't, and what it's worth to you in dollars.
As of this writing, the settlement has preliminary court approval. Final approval and the exact start dates are still pending, and some merchant groups have said they'll appeal.
What is the Visa Mastercard settlement?
It settles a long-running class action by merchants who said Visa and Mastercard's rules kept swipe fees high. In June 2026, a federal judge in Brooklyn gave the deal preliminary approval. It covers roughly 12 million merchants, which means if you take Visa or Mastercard, it probably covers you.
What changes for merchants?
Slightly lower credit card interchange. Credit interchange rates come down by about 0.10 percentage points, for five years.
A cap on standard consumer cards. Interchange on standard, non-premium consumer credit cards gets capped at 1.25% for eight years.
You can turn down some premium cards. Merchants get the option to decline certain high-cost premium and commercial credit cards. That's a big change from the old "honor all cards" rule.
More room to surcharge or discount by card type. Merchants get new rights to add surcharges or offer discounts on certain cards to steer customers toward cheaper ways to pay.
What doesn't change?
Debit cards. You still can't surcharge debit or prepaid cards.
State law. If your state bans surcharging, like Connecticut does, the settlement doesn't override that.
Your processor's markup. The settlement lowers what the card brands charge. It doesn't force your processor to lower the padding they put on top. If they don't pass the savings along, you won't see them.
Amex and Discover. This deal is about Visa and Mastercard.
How much will the Visa Mastercard settlement save me?
Let's run the numbers. Say you do $50,000 a month in credit card sales.
A 0.10% drop on $50,000 is $50 a month.
That's about $600 a year, if your processor passes every cent along.
Worth having. But compare that to what you're paying now. At a 3% effective rate, that same $50,000 costs you $1,500 a month, or $18,000 a year. The settlement trims about 3% of that bill. You'd still be paying around $17,400.
"How much will I get?" Is there a payout?
A lot of people searching this are thinking of a check. This settlement is mainly about lowering fees and changing rules going forward. If you're looking for a payout for fees you paid in the past, that's tied to a separate, earlier class-action settlement with its own official website and claims process. Be careful with anyone who calls offering to "file your claim" for a cut of the money.
Should I start declining premium cards or surcharging?
Slow down. Turning away a customer's card at the register costs you more than the fee if they walk out. And surcharging still means card-network notice, signage, receipt rules, and state law, including an outright ban in Connecticut.
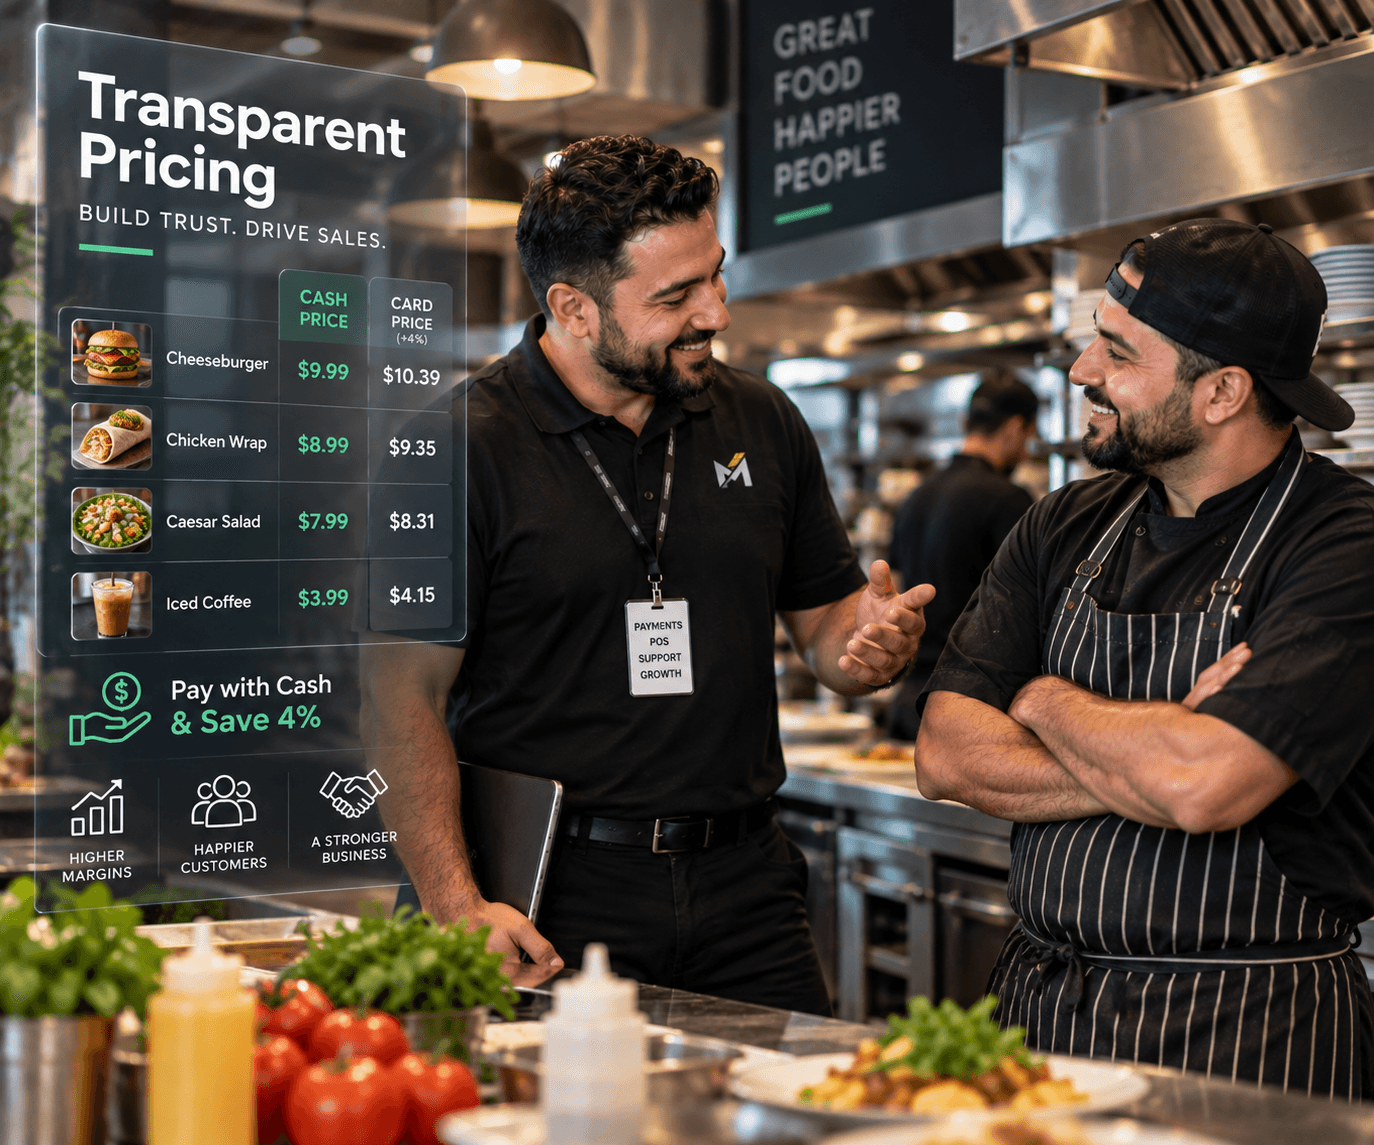
For most local businesses, a properly set up dual pricing program is the cleaner move. Both prices are posted upfront, every card is accepted, and the card price covers the processing cost. That doesn't save you $600 a year. It can save you most of the $18,000.
What else is coming?
Congress is also looking at swipe fees. The Credit Card Competition Act was reintroduced in the Senate in January 2026. It would require big banks' credit cards to run on at least one network besides Visa or Mastercard. It hasn't passed, and it's been introduced before. We'll update you if it moves.
Quick answers
What is the Visa Mastercard settlement? A $38 billion class-action settlement over swipe fees that lowers some interchange rates and gives merchants more control over which cards they accept and how they price them.
When does the Visa Mastercard settlement take effect? It received preliminary approval in June 2026. Changes start after final approval, which is still pending.
Will my processing fees go down? A little, if your processor passes the savings along. Roughly 0.10 percentage points on credit cards.
Can I surcharge debit cards now? No. Debit surcharges are still not allowed.
Find out what you're really paying
Want to know if your processor is actually going to pass these savings on to you? Let's look at your statement together.
Send us one recent statement. We'll show you your real rate, where the padding is, and exactly what you'd keep with dual pricing. No contract, no cancellation fee, and a real person on the phone.
Call 888-411-7583 or get your free savings quote.
MTech Distributors has helped 5,000+ businesses across all 50 states since 2017.